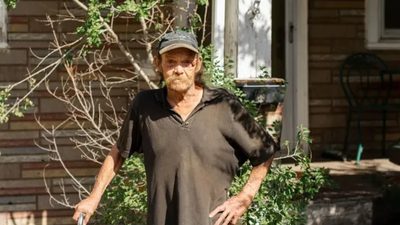
A legal fight over homeownership and tax liens in Nebraska reached a major turning point when the state’s highest court revived a compensation claim from a couple who lost their mortgage-free home over a relatively small tax debt. Kevin Fair and his wife, Terry, owned a home in Scotts Bluff County with no mortgage or other liens. The property was valued by the county at $59,759. After the couple failed to pay $588.21 in property taxes, the county sold the tax debt to Continental Resources. The dispute eventually reached the US Supreme Court before returning to the Nebraska Supreme Court. In 2024, the Nebraska court ruled that Fair had a valid claim that he was deprived of property without just compensation.
Debt swells and deed changes hands
The case began in 2015, when the Scotts Bluff County treasurer sold a tax certificate for the unpaid $588.21 to Continental Resources on March 11. Nebraska law allowed the county to sell the tax certificate to a private buyer. Continental then paid later property taxes on the home. The county stopped sending the Fairs further tax bills after Continental began making those payments. Three years later, on April 13, 2018, Continental sent the couple a “Notice of Expiration of Right of Redemption.” The notice gave them three months to recover the property by paying $5,268, which represented the unpaid taxes, interest, fees, and other costs. The Fairs did not pay the amount within the three-month period. In July 2018, Continental applied for a tax deed, and the county treasurer issued the deed to the company. At that time, the county assessed the property at $59,759. The deed transferred the property to Continental free of the Fairs’ ownership interest.
District court and initial appeals
Continental then filed a quiet title case in state court to establish its ownership. Kevin Fair responded with a counterclaim and a third-party complaint against Scotts Bluff County and the county treasurer. The Nebraska Attorney General also took part because Fair was challenging the constitutionality of state laws. Fair argued that taking a property worth $59,759 to satisfy a tax debt of $5,268 amounted to an unconstitutional taking without just compensation under both the US and Nebraska Constitutions. He also raised claims under the Due Process Clauses, the Excessive Fines Clause of the US Constitution, and other provisions of the Nebraska Constitution. The District Court for Scotts Bluff County granted summary judgment for Continental and rejected Fair’s constitutional claims. Fair appealed. In 2022, the Nebraska Supreme Court initially upheld the lower court’s decision, ruling that Nebraska’s tax certificate system was not unconstitutional in the ways Fair had argued.
US Supreme Court intervenes
Fair then asked the US Supreme Court to review the case. While that request was pending, the US Supreme Court decided Tyler v. Hennepin County in 2023. In Tyler, the Court held that a homeowner could have a constitutional takings claim when a government takes property to pay a tax debt and keeps the property’s value above the amount owed. The US Supreme Court later granted review in Fair’s case, vacated the Nebraska Supreme Court’s earlier ruling, and sent the case back to Nebraska for reconsideration in light of Tyler v. Hennepin County. The case remained docketed as S-21-074.
State supreme court revives claim
After reviewing the case again, the Nebraska Supreme Court reversed the lower court’s summary judgment on Fair’s takings claim. The decision was issued on August 23, 2024, in Continental Resources v. Fair, 317 Neb. 391. According to the Nebraska Supreme Court’s opinion, Fair had a protected property interest in the value of his home above the amount of his tax debt. The court said that if the property was worth more than the debt, taking that extra value without paying Fair could amount to a taking without just compensation. The court also concluded that Continental could potentially be responsible for paying that compensation. The justices found that Continental’s decision to seek the tax deed was sufficiently connected to the state tax system to count as state action for purposes of Fair’s takings claim. The court therefore sent that claim back for further proceedings. The court did not revive Fair’s other constitutional claims. It upheld summary judgment for Continental and the county on those claims, including the Excessive Fines claim.
Impact on local tax practices
Under the Nebraska tax certificate system that applied in 2015, a county could sell a tax certificate for unpaid property taxes to a private buyer. If the owner did not redeem the property within the required period, the certificate holder could seek a tax deed and obtain the property. The Nebraska Supreme Court noted that the laws governing this process were substantially changed in later years. The court’s 2024 ruling did not award Fair a specific amount of money. Instead, it found that genuine factual issues remained over his claim for just compensation and sent the case back to the district court for further proceedings. The court also ruled that Scotts Bluff County was entitled to summary judgment on that claim, while leaving the question of possible state liability undecided.