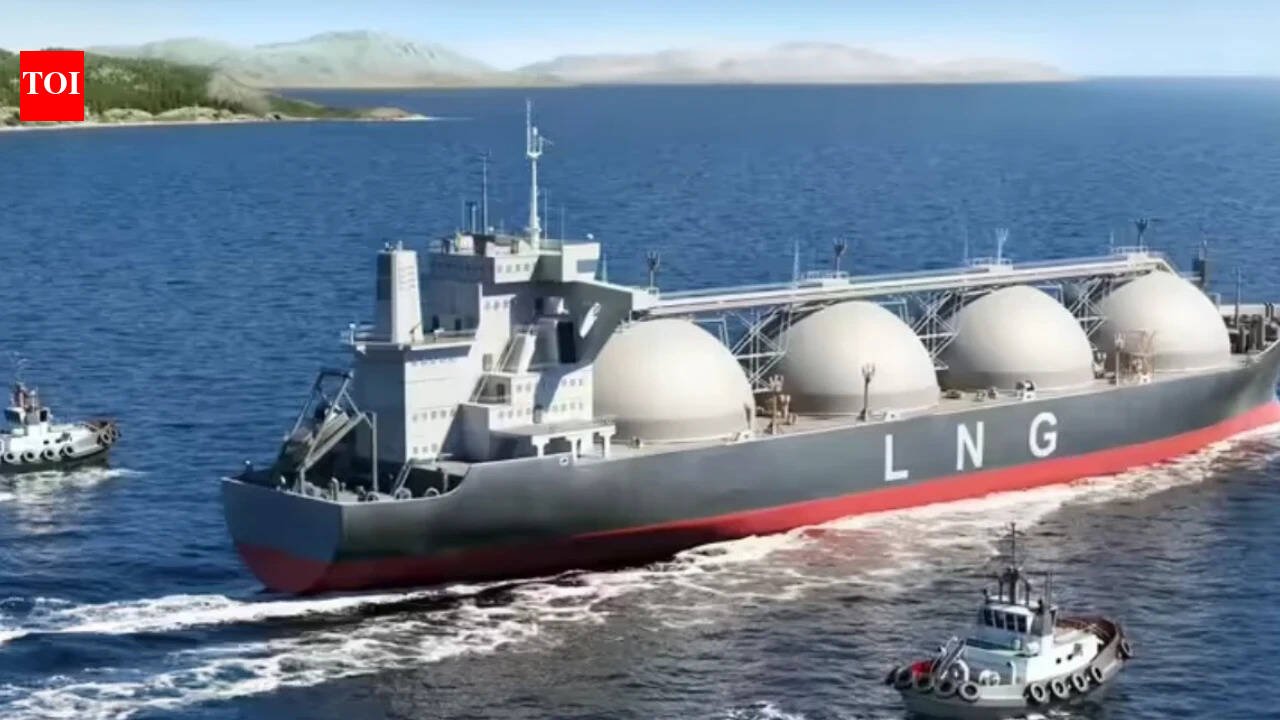
Global energy markets continue to face supply disruptions, with higher LNG prices, rising crude transportation costs and narrowing discounts on Russian oil adding to cost pressures. LNG prices have climbed 6% week-on-week to an average of $32 per million British thermal units (mmBtu), while lower gas inventories in Europe are raising concerns about affordability in India as winter approaches, according to a report by Jefferies.The report also highlighted the impact of continued disruptions in crude oil supply chains, despite a recovery in Middle Eastern exports. Higher freight rates and crude premiums have kept procurement costs elevated, while Indian oil marketing companies (OMCs) continue to face significant losses on petrol and diesel.The outlook for global liquefied natural gas (LNG) prices remains firm as Europe enters the winter season with lower gas inventories than last year. European Union (EU) gas storage levels currently stand at 75%, against 83% during the same period last year.This comes as spot LNG prices have increased 6% week-on-week to an average of USD 32 per mmBtu, raising concerns over the affordability of imported gas in India.“Domestic affordability is stretched at current prices,” the report noted, adding, “Hence, we expect gas prices to remain elevated as we head into winter.”
Crude shipments face disruptions despite recovery in Middle Eastern exports
The recovery in crude oil exports from the Middle East has not fully eased supply-side disruptions in global markets. Exports from the region, excluding Iran, have recovered to more than 90% of pre-war levels. However, renewed attacks have pushed the physical crude premium up 8% week-on-week to $9 per barrel last week.The movement of crude oil has also become more complicated, with shipments spending longer periods aboard tankers and importers taking longer routes to diversify their supplies.“Crude oil-in-transit has reached an all-time high as ship-to-ship transfers are keeping oil aboard tankers for longer and importers are opting for lengthier routes to diversify away from the ME.”These changes have kept transportation costs significantly above pre-conflict levels. Although freight rates declined 3% week-on-week, they remain nearly eight times higher than at the beginning of the conflict.Freight now accounts for more than 25% of the landed cost of crude oil, compared with just 3% before the war.“Freight rates could remain elevated in the near term with multiple attacks on oil tankers,” the report said.
Narrowing Russian crude discounts add to OMCs’ burden
Indian oil marketing companies continue to face elevated crude procurement costs as discounts on Russian oil have narrowed considerably.Russian Urals crude is now trading at a discount of USD 2 per barrel to Brent, compared with USD 14 per barrel at the end of February. At the same time, the discount on Dubai crude against Brent widened sixfold week-on-week to USD 4 per barrel.With procurement costs for Indian OMCs remaining broadly aligned with the Indian crude basket price of USD 118 per barrel, the companies are facing substantial marketing losses on petrol and diesel.“Procurement costs for OMCs are similar to the Indian crude basket price of US$118/bbl, resulting in steep losses,” Jefferies said, adding, “Current loss of petrol/diesel is Rs25/37 per lt based on 15-day average pricing.”
Russian supply disruptions expected to support margins through FY27
The report also flagged the impact of Ukrainian attacks on Russian refining infrastructure, which have reduced Russian exports and tightened the supply of middle distillates.With these disruptions affecting the availability of supplies, a return to normal supply conditions is expected to take time.“Normalization of supply chains is likely to take time, supporting elevated margins over FY27,” the report said.Meanwhile, disruptions to petrochemical supplies from the Middle East have contributed to an improvement in margins across the sector.Two major facilities each in Iran and Saudi Arabia have suffered damage, while shipments of naphtha from the Middle East to Northeast Asia continue to face disruptions.The impact is reflected in the movement of petrochemical margins. Average margins across polyethylene (PE), polypropylene (PP) and polyethylene terephthalate (PET) have risen 55% compared with levels at the end of February.According to Jefferies, “Average petchem margins (PE/PP/PET) are currently up 55% vs February-end, aiding Reliance’s O2C profitability.”