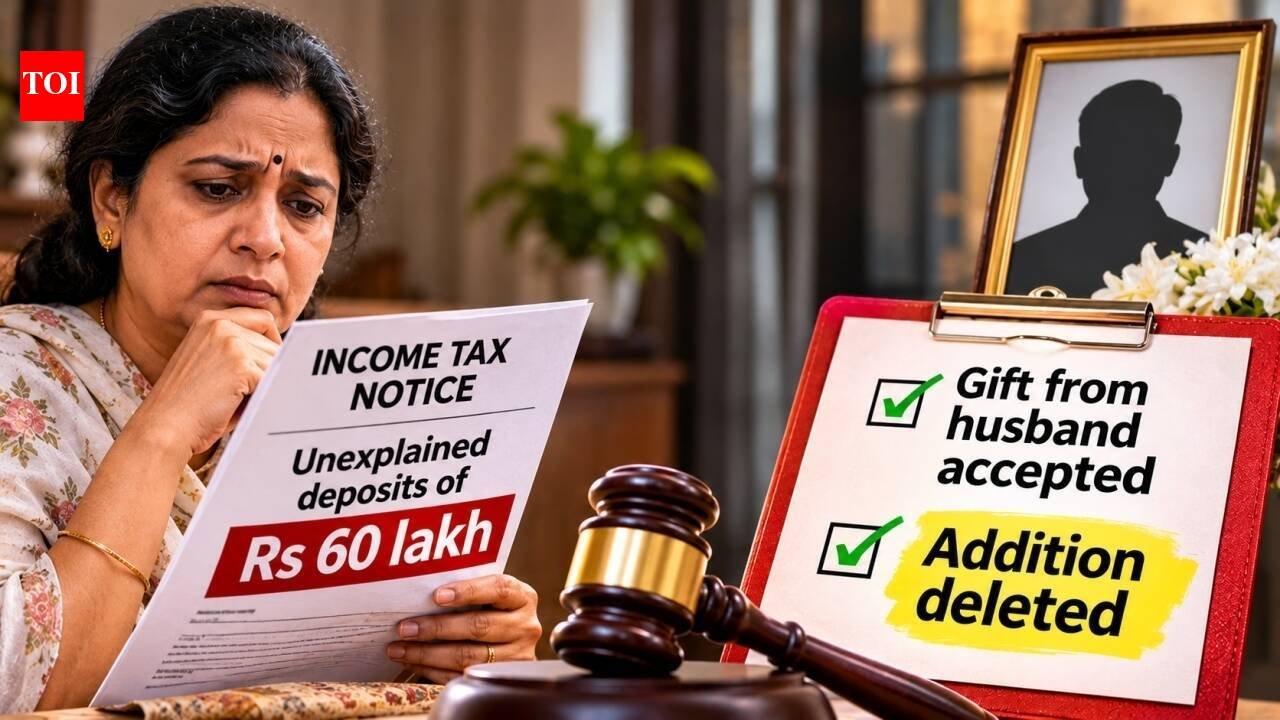
Your husband deposits money in your account as a gift for you and your daughters but then passes away. Are you liable to pay tax on the deposit?In one such case the Income Tax Department sent a notice to a widow treating a cash deposit of Rs 60 lakh as unexplained income. However, the Income Tax Appellate Tribunal (ITAT) Pune ruled in her favour.The case underlines why taxpayers should retain relevant documents to substantiate the source of money in their bank accounts.
What the case is about
The Income Tax Department discovered that a woman’s bank account had seen a cash deposit of Rs 60,07,500 during the financial year 2015-16. However, she had not filed an income tax return (ITR) for the corresponding assessment year.The Assessing Officer (AO) subsequently issued a show-cause notice under Section 148A(b) of the Income Tax Act, 1961. As the woman did not respond, the AO passed an order.The department then sent further notices asking her to furnish details about the cash deposits. Since no documentary evidence had been provided, the AO issued another show-cause notice, seeking an explanation for why the assessment should not be completed on the basis of the information already available on record.The widow responded by filing her ITR in 2024, declaring a total income of Rs 12,000. Along with the return, she submitted an explanation that the Rs 60 lakh deposited in her account was a gift from her deceased husband. She also explained that she had been unable to collect the necessary documents.According to the woman, her husband died in 2023. He had deposited the money in her bank account as a gift intended for her and their two minor daughters.The widow maintained that the Rs 60 lakh deposited in her bank account was a gift from her late husband intended for the family, including their two minor daughters. She argued that the amount should not be treated as taxable income in her hands.The Assessing Officer, however, pointed out that the assessee’s bank account contained unexplained credits totalling Rs 75 lakh. These comprised a cash deposit of Rs 60 lakh and clearing cheque credits of Rs 15 lakh. Since the woman had not furnished evidence establishing the source of the cash, the AO treated the Rs 60 lakh as unexplained money and added it to her income under Section 69A.The woman’s counsel submitted that she was a housewife who had never filed an income tax return because she had no independent source of income.To substantiate her explanation, Ms Parve furnished several documents, including Form 26AS, an affidavit, her husband’s death certificate, a computation sheet and bank statements.
Why did ITAT rule in the widow’s favour?
The tribunal considered that the woman’s husband, who had allegedly gifted the Rs 60 lakh to her and their two minor daughters, had passed away and was therefore no longer available to provide a confirmation, affidavit or explanation regarding the transaction.It also observed that the widow had met the initial burden of establishing the donor’s identity and her relationship with him. The documents and explanations submitted included his PAN details and confirmations from their two daughters regarding the gift.The woman was able to explain the source of the money and establish her relationship with the person who had given it to her. She submitted her late husband’s death certificate and PAN details, along with her own affidavit and confirmations from both daughters.Explaining the significance of the evidence, Advocate Shourya Garg, Founder of Garg & Garg Tax Associates, told ET: “The Tribunal said she had done enough to prove the donor’s identity and the relationship, and the department had not shown her documents to be false. It also did not accept that section 69A means an automatic addition,”With her husband no longer alive to personally confirm the transaction, the tribunal accepted her explanation that the money had been gifted by him and ordered the deletion of the addition.Accepting the explanation that the Rs 60 lakh cash deposit represented a gift from her late husband to her and their two daughters, the tribunal concluded that the addition under Section 69A was not justified. ITAT Pune accordingly directed the AO to delete the addition of Rs 60 lakh.Garg advised people to begin collecting the relevant paperwork as early as possible, while documents and details of past transactions are still accessible. Important records to preserve include the deceased person’s death certificate and legal heir certificate, bank statements, passbooks, fixed deposit receipts, previous income tax returns and PAN details.If the deceased family member had given you money or made gifts, maintain a written record of the transactions, including their dates and amounts. Garg said that a straightforward, signed gift letter and written confirmations from other family members could prove useful if questions arise later.He also recommended registering as a legal heir on the income tax portal to access the deceased person’s tax filings. For gifts made in the future, he advised using bank transfers instead of cash.